

Taking some chips off the table
8 mins to read this article

What you need to know
-
We remain positive about the medium-term outlook: the global economy is expanding, corporate profits are growing and investment in AI continues to support economic activity.
-
The near term looks less straightforward: higher oil prices, geopolitical tensions and the approaching US midterm elections have widened the range of possible outcomes at a time when several markets have already performed strongly.
-
We are taking some profits and adding resilience: after strong gains, we are closing our tactical overweight in emerging market equities and increasing our exposure to US Treasuries. This reflects the changing balance of risks rather than a less positive view of the longer-term opportunities.
Note: Any reference to portfolio positioning relates to our flagship core discretionary portfolios. Clients invested in other strategies, or in bespoke and advisory portfolios, should consult their Client Advisor.
A good outlook does not mean taking every risk
There is still plenty to like about the medium-term investment outlook. The global economy is growing despite rising energy prices, higher interest rates and political uncertainty. Corporate profits are also growing, supported by the significant investment in building the infrastructure behind AI.
This is why we still have a positive view on equities. It’s also why we don’t believe we’re in an AI bubble. Demand for computing power, cloud infrastructure and advanced semiconductors is generating revenues and earnings across the technology supply chain. Over time, we believe the potential productivity benefits can extend well beyond the technology sector.
However, as the sums involved become larger, the economics deserve closer attention. Questions are increasingly being asked about how AI projects are financed, whether future revenues can justify the money being committed and what returns they can ultimately generate.
We also expect the extraordinary pace of AI spending growth to ease. As the investment base grows, maintaining the same rate of expansion requires ever larger amounts of capital. Our central scenario is therefore for spending to continue rising, but at a slower pace.
Spending can therefore grow more slowly without signalling the end of the AI investment cycle. We continue to see AI as a powerful long-term investment theme, even as the economics of individual projects and companies come under greater scrutiny. The longer-term outlook remains supportive, but the risks over the coming months have increased.
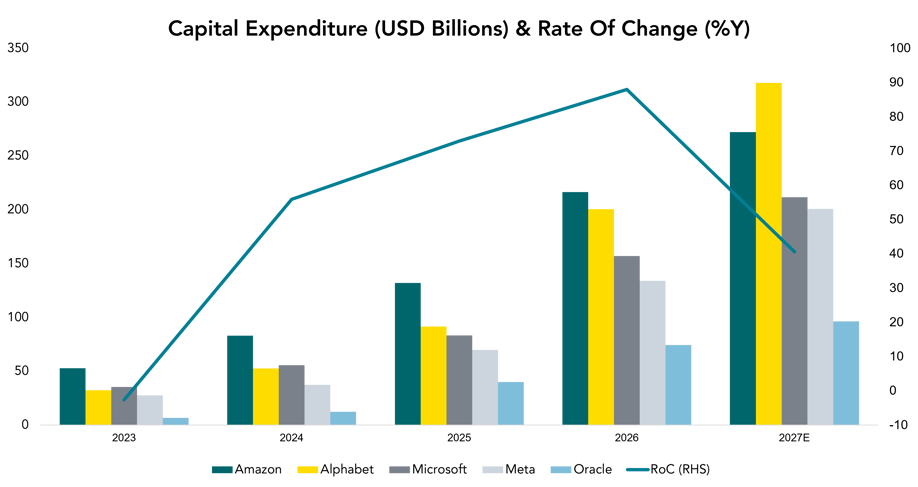
Source: In-house Research, LSEG Datastream. Past performance is not a reliable indicator of future returns.
The balance of risks has shifted
There is never a dull moment on the news flow front. Cristine Lagarde’s decision to step down as European Central Bank President in February 2027, nine months before the end of her term, might add some uncertainty in the near term. However, it also allows current European leaders to choose her successor. At the same time, the French elections could continue to grab market attention, putting upward pressure on bond yields if no credible path towards fiscal adjustment and economic reform emerges.
More fundamentally, one area where the outlook has become less favourable is energy. The decline in oil prices we had anticipated as tensions in the Middle East eased has not materialised. A further disruption could send energy prices higher, putting renewed pressure on inflation, household finances and company costs while making central-bank decisions more difficult.
The approaching US midterm elections introduce another source of uncertainty. A more divided government could constrain further fiscal expansion, while the political consequences of the result could also shape US foreign policy and negotiations in the Middle East.
Neither development overturns our central economic outlook. But they come at a time when several markets have already risen substantially, raising the hurdle for taking additional risk. Investors need to consider not only what is most likely to happen, but how much optimism is already reflected in prices and whether the potential return still provides sufficient compensation if events develop differently.
This is where our view on emerging markets has changed.
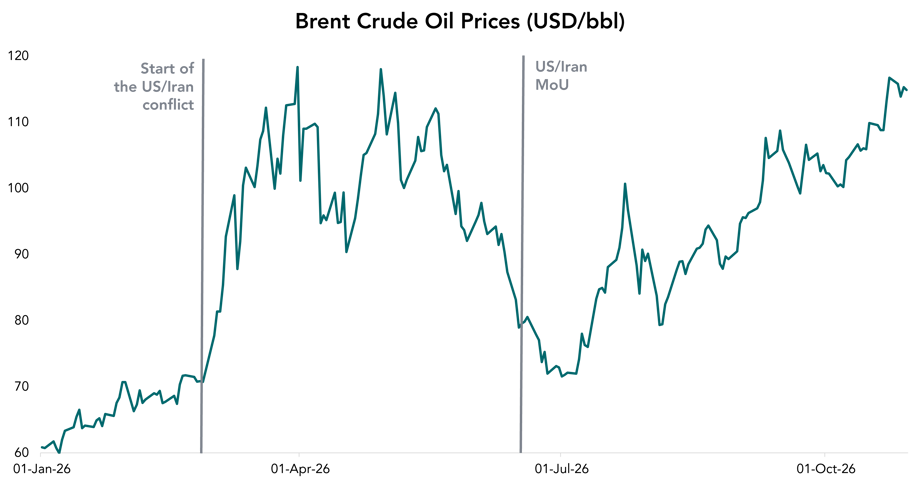
Source: In-house research, LSEG Datastream. MoU = Memorandum of Understanding for ceasefire. Past performance is not a reliable indicator of future returns.
Why we are taking profits in emerging markets
Our overweight position in emerging market equities has performed well. Improving earnings, strong Asian markets and exposure to the global technology cycle have all helped.
We are now taking some profits and returning to a neutral position. But we are not walking away from emerging markets.
We still see attractive long-term opportunities, particularly in Asian technology companies and the semiconductor supply chain. We also remain positive on the longer-term AI investment cycle. However, there are two reasons why we think the near-term balance between risk and potential return has become less attractive.
Firstly, technology makes up a large part of the emerging market equity universe. That exposure has supported performance as AI investment has grown, while giving investors another way to participate in the theme beyond the large US technology companies. But it also means US and Asian technology markets are increasingly exposed to the same questions from investors about AI spending and the returns it can ultimately generate.
Secondly, many of the Asian markets we invest in are particularly exposed to higher oil prices. The largest Asian emerging markets are oil importers, making them vulnerable to a further rise in prices if tensions in the Middle East escalate. If that were accompanied by a stronger US dollar or investors pulling money out of emerging markets, the pressure could become more pronounced.
Being positive about emerging markets over several years does not mean maintaining an overweight position at every point in the cycle. For now, we believe a neutral allocation is more appropriate.
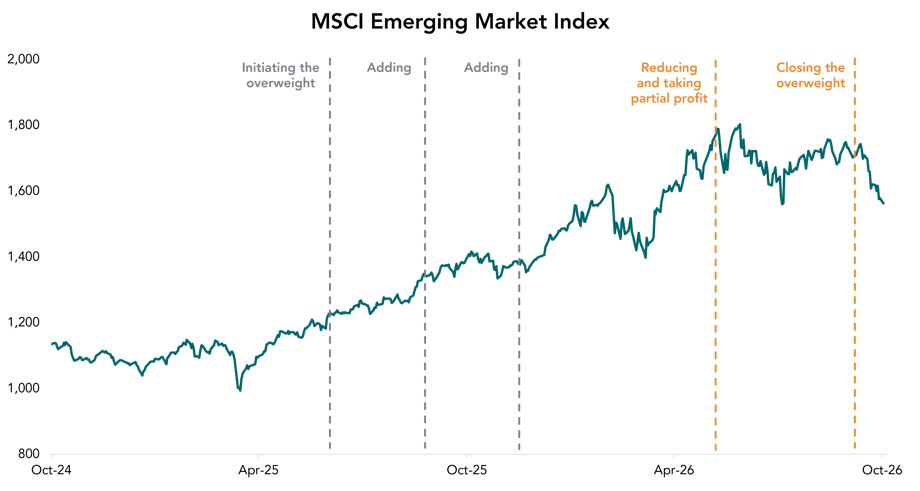
Source: In-house research, LSEG Datastream. Past performance is not a reliable indicator of future returns.
Adding to US Treasuries while staying selectively constructive
We are reallocating the proceeds into US Treasuries, hedged into local currency to remove the impact of exchange-rate movements. This builds on our recent decision to reduce European government bonds and increase exposure to US Treasuries.
The aim is to improve portfolio resilience and capture yield. US Treasuries can help diversify our equity exposure and may perform well if growth slows, geopolitical tensions rise or equity markets become more volatile. They could also benefit if the US midterm elections result in a more divided government, making further increases in government spending less likely.
Treasuries don’t protect portfolios in every scenario. A further oil shock, for example, could push inflation expectations and bond yields higher, reducing their defensive qualities. Even so, we believe they provide a useful counterweight to some of the risks we currently see.
None of these changes alters our constructive medium-term outlook. They reflect a judgement that, after a period of strong returns, some of the risks have become less attractive to take today.
For us, this argues for taking some chips off the table: realising gains where markets have rewarded us, retaining exposure to the opportunities we continue to believe in and adding some resilience if the months ahead prove less straightforward.
We take time to listen
Thank you for reading our monthly update.
Please contact us if you have any questions, remarks or suggestions regarding this update.
Take a look at our other publications below:
Always there for you wherever you are
At Quintet, we pride ourselves on being small enough to really get to know you, yet big enough to give you easy access to the best the world of finance has to offer. Whatever your needs, we will provide objective insights, advice, products and services tailored to your personal goals. And with offices in 30+ cities across Europe and the UK we are always there for you wherever you are. Why not come and talk with us today?
This document is designed as marketing material. This document has been composed by Quintet Private Bank (Europe) S.A., a public limited liability company (société anonyme) incorporated under the laws of the Grand Duchy of Luxembourg, registered with the Luxembourg trade and company register under number B 6.395 and having its registered office at 43, Boulevard Royal, L-2449 Luxembourg (“Quintet”). Quintet is supervised by the CSSF (Commission de Surveillance du Secteur Financier) and the ECB (European Central Bank).
This document is for information purposes only, does not constitute individual (investment) advice and investment decisions must not be based merely on this document.
Whenever this document mentions a product, service or advice, it should be considered only as an indication or summary and cannot be seen as complete or fully accurate. All (investment) decisions based on this information are at your own expense and at your own risk. It is up to you to (have) assess(ed) whether the product or service is suitable for your situation. Quintet and its employees cannot be held liable for any loss or damage arising out of the use of (any part of) this document. All copyrights and trademarks regarding this document are held by Quintet, unless expressly stated otherwise. You are not allowed to copy, duplicate in any form or redistribute or use in any way the contents of this document, completely or partially, without the prior explicit and written approval of Quintet. See the privacy notice on our website for how your personal data is used (https://www.quintet.com/en-gb/gdpr).
The contents of this document are based on publicly available information and/or sources which we deem trustworthy. Although reasonable care has been employed to publish data and information as truthfully and correctly as possible, we cannot accept any liability for the contents of this document.
Investing involves risks and the value of investments may go up or down. Past performance is no indication of future performance. Any projections and forecasts are based on a certain number of suppositions and assumptions concerning the current and future market conditions and there is no guarantee that the expected result will ultimately be achieved. Currency fluctuations may influence your returns.
The information included is subject to change and Quintet has no obligation after the date of publication of the text to update or inform the information accordingly.
Copyright © Quintet Private Bank (Europe) S.A. 2026. All rights reserved. Privacy Statement