

America Votes: Preparation, Not Prediction
5 mins to read this article


The US midterm elections on 3 November will generate no shortage of headlines. Attention will focus on who wins, who loses and what the result means for President Trump's second term.
For portfolios, we think a different question matters more.
What happens if Washington becomes less able to make major policy changes?
We think, based on current polling and prediction markets, that a divided government is the most likely outcome. Democrats appear to have a realistic chance of regaining control of the House while the Senate remains closely contested. If that proves correct, the second half of Trump's presidency could be defined more by political constraint than political change.
That may sound like a political story. We see it as an economic one.
A Petrol Receipt Can Tell Part of the Story
Like us in Europe, many Americans are feeling things getting more expensive, especially at the pump.
Many US households see the impact of higher oil prices every time they fill their cars. Rising fuel costs can influence consumer confidence, spending decisions and perceptions of inflation. Unsurprisingly, they can also influence political sentiment. This year, we have observed a notable correlation between US gasoline prices and betting market odds for the Democrats taking over Senate control following the midterms.
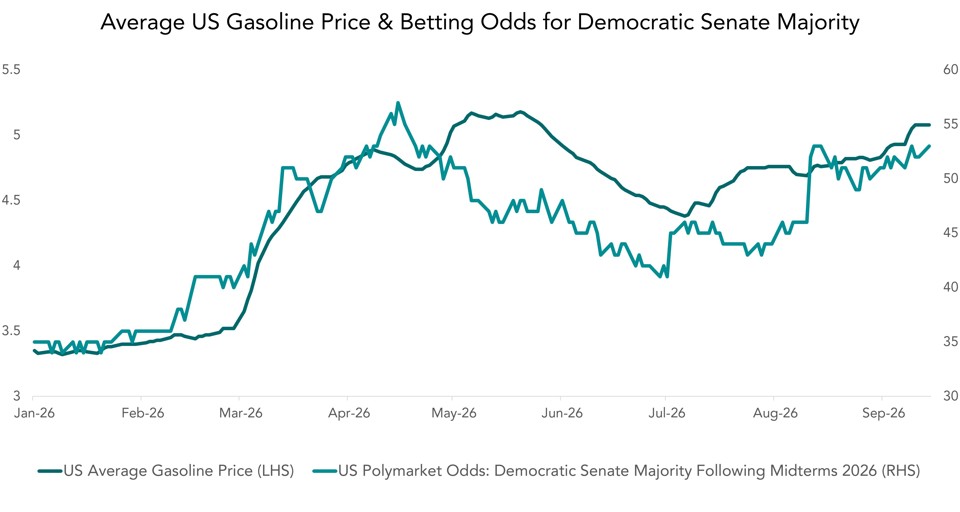
Sources: In-house research, Bloomberg, Polymarket
Based on this correlation, if oil prices remain elevated or rise further, the probability of a Democratic Senate majority may also increase. Combined with a House majority, this would produce a ‘Blue Sweep’, which would limit the Trump Administration’s power to change legislation in the second half of the President’s term. It could also mean less fiscal support and fewer deregulation measures than markets had anticipated.
Developments in the US-Iran war therefore matter for markets. The conflict’s effect on energy prices could add to inflation pressures, possibly leading to bond yields rising further. In turn, it can affect borrowing costs, company valuations and asset prices more broadly.
Our Base Case: Divided Government
Current indicators suggest that continued Republican control of both chambers is unlikely.
Surveys and betting markets appear to mirror the effects of latest energy and inflation trends. The Democrats are expected to win the House, while the odds for a Senate majority are on the rise. Our base case remains a divided government. However, the estimated probability of a ‘Blue Sweep’ has increased recently.
SCENARIOS FOR THE MIDTERMS
A divided government following the midterms is our base case, with betting markets also indicating a significant chance for a Democratic sweep.
BASE CASE
Divided government
Historically viewed as market-friendly, with less policy uncertainty and fewer major legislative changes than in the period before the midterms.
CONTINUITY
Republican control
Trump can continue pursuing tax cuts, deregulation and further trade measures with congressional support.
Source: In-house research and estimates
POLICY SHIFT
Democratic sweep
More regulation and less support for fossil fuels are likely; the fiscal and tax outlook is less clear, with greater social-welfare protection.
Both a ‘Blue Sweep’ and a divided Congress could reduce the likelihood of additional fiscal stimulus and major deregulation measures. This could create a more cautious backdrop for sectors that are particularly sensitive to policy changes. By comparison, businesses whose prospects depend more on their competitive strengths than on political outcomes may benefit.
If Congress becomes more constrained, we expect markets to place less emphasis on policy changes and more on company fundamentals. Earnings resilience, balance-sheet strength and cash-flow generation could become increasingly important drivers of returns.
The Election is only the Starting Point
A useful way to think about the election is as the start of a process rather than the end of one.
The result may not only alter expectations for government spending, taxation or regulation. It can influence forecasts for growth and inflation. Changes in growth and inflation expectations can then affect bond yields, interest-rate expectations and stock markets. The election itself is only one link in that chain.
This is why markets sometimes react very differently to election results that appear similar on the surface. The broader economic backdrop often matters more than the politics.
For portfolios, the key question is not which party gains seats. It is whether the outcome changes the economic environment in a meaningful way.
From a fundamental perspective, we do not expect this scenario to have a material effect on the earnings trend, meaning broad US equities should remain well positioned. While historical patterns never guarantee future returns, the year following midterm elections has often been one of the stronger periods in the US presidential cycle. As election uncertainty fades, markets tend to refocus on earnings, economic growth and monetary policy.
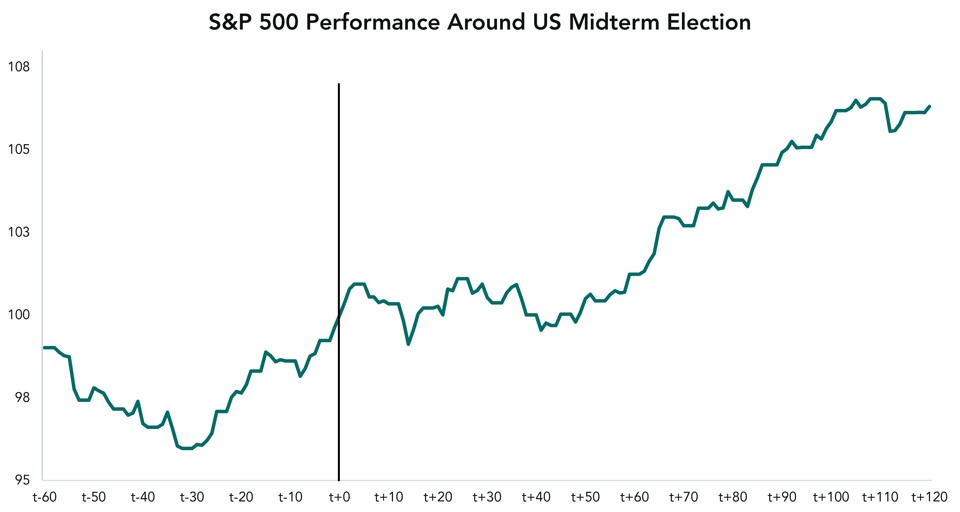
Source: In-house research, LSEG Datastream. Past performance is not a reliable indication of future performance.
Why High-Quality Bonds Still Matter
A divided government could also reinforce the case for high-quality fixed income.
If legislative gridlock reduces the likelihood of significant fiscal expansion, inflation and interest-rate expectations may become even more important for markets. At the same time, elevated yields mean bonds once again offer a meaningful source of income in their own right.
In a market environment where uncertainty remains elevated, that combination remains attractive.
The Investment Story Beyond Election Night
As election day approaches, attention will naturally focus on who controls Congress.
Our focus is elsewhere. We believe the most likely outcome is a divided government and that such an environment would place greater emphasis on company quality, earnings resilience and the path of interest rates.
The election result will determine the political story. For portfolios, the more important story may be what happens once the campaigning ends and markets return their attention to fundamentals.
Always there for you wherever you are
At Quintet, we pride ourselves on being small enough to really get to know you, yet big enough to give you easy access to the best the world of finance has to offer. Whatever your needs, we will provide objective insights, advice, products and services tailored to your personal goals. And with offices in 30+ cities across Europe and the UK we are always there for you wherever you are. Why not come and talk with us today?
This document is designed as marketing material. This document has been composed by Quintet Private Bank (Europe) S.A., a public limited liability company (société anonyme) incorporated under the laws of the Grand Duchy of Luxembourg, registered with the Luxembourg trade and company register under number B 6.395 and having its registered office at 43, Boulevard Royal, L-2449 Luxembourg (“Quintet”). Quintet is supervised by the CSSF (Commission de Surveillance du Secteur Financier) and the ECB (European Central Bank).
This document is for information purposes only, does not constitute individual (investment) advice and investment decisions must not be based merely on this document.
Whenever this document mentions a product, service or advice, it should be considered only as an indication or summary and cannot be seen as complete or fully accurate. All (investment) decisions based on this information are at your own expense and at your own risk. It is up to you to (have) assess(ed) whether the product or service is suitable for your situation. Quintet and its employees cannot be held liable for any loss or damage arising out of the use of (any part of) this document. All copyrights and trademarks regarding this document are held by Quintet, unless expressly stated otherwise. You are not allowed to copy, duplicate in any form or redistribute or use in any way the contents of this document, completely or partially, without the prior explicit and written approval of Quintet. See the privacy notice on our website for how your personal data is used (https://www.quintet.com/en-gb/gdpr).
The contents of this document are based on publicly available information and/or sources which we deem trustworthy. Although reasonable care has been employed to publish data and information as truthfully and correctly as possible, we cannot accept any liability for the contents of this document.
Investing involves risks and the value of investments may go up or down. Past performance is no indication of future performance. Any projections and forecasts are based on a certain number of suppositions and assumptions concerning the current and future market conditions and there is no guarantee that the expected result will ultimately be achieved. Currency fluctuations may influence your returns.
The information included is subject to change and Quintet has no obligation after the date of publication of the text to update or inform the information accordingly.
Copyright © Quintet Private Bank (Europe) S.A. 2026. All rights reserved. Privacy Statement