

Central banks are still worried about inflation
4 mins to read this article
Daniele Antonucci
Daniele Antonucci is a managing director, head of investment and chief strategist at Quintet Private Bank. Based in Luxembourg, he chairs the investment committee, owning performance outcomes, and has responsibilities across research and strategy, asset allocation, portfolio management and investment communications.
Daniele’s work brings together global macro strategy with investment decision-making and thought leadership. He leads specialists across asset classes and solutions, and formulates and communicates investment views and the economic and market outlook to financial advisors, clients, senior stakeholders and the media.
Daniele joined Quintet in 2020 as chief economist and macro strategist, subsequently becoming co-head of investment and chief investment officer. He previously served as chief euro area economist at Morgan Stanley in London, having also gained international experience with other global investment banks, helped deliver strategic partnerships with leading asset managers such as BlackRock, and held positions at economic consultancies, rating agencies and think tanks.
Daniele completed the High Performance Leadership Programme at Saïd Business School, University of Oxford, earned a master’s degree in economics from Duke University and graduated from Sapienza University of Rome. A lecturer at the Luxembourg School of Business, he is a published author in economics journals, a frequent contributor to global investment media, a speaker on CNBC and Bloomberg TV, and an ECB Shadow Council member.

What matters to you in 30 seconds
-
Central banks might not be done yet. We expect one more US rate hike this year as higher energy prices keep inflation under pressure, but not the start of a new tightening cycle.
-
Higher rates have not derailed markets. Economic growth and corporate earnings remain resilient, supporting our preference for equities while higher bond yields are improving income opportunities.
-
The focus now shifts to the data. Upcoming economic indicators will show whether growth can continue to hold up despite higher borrowing costs and elevated energy prices.
Chart of the week
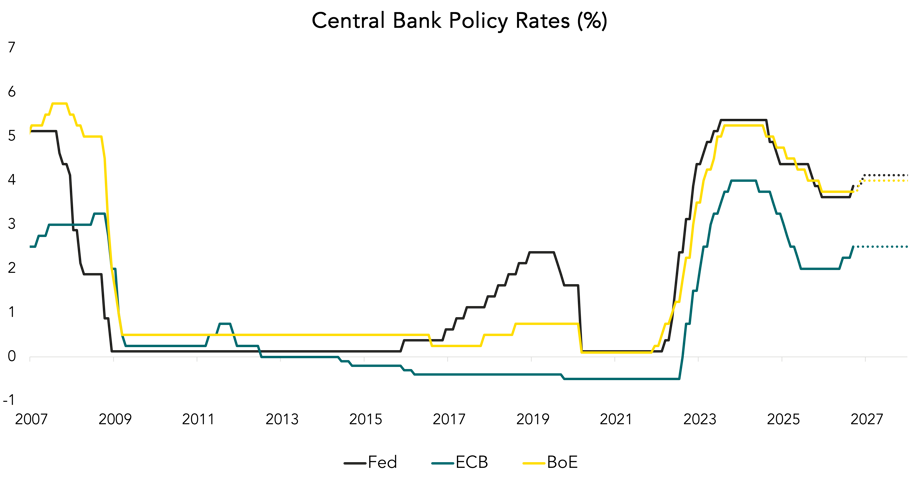
Source: In-house research, LSEG Datastream. Dotted lines = in-house forecasts
More rate hikes, but not necessarily a new cycle
Last week, the US Federal Reserve (Fed) and the Bank of Japan (BoJ) raised interest rates by 25 basis points, reflecting continued concerns about inflation. In the US, the Federal Funds Rate now stands at 3.75%-4.00%, and policymakers have indicated that further increases are possible if inflation doesn’t ease.
The Bank of England (BoE) took a different approach last week, holding the base rate at 3.75%. It also announced a significant shift in its Quantitative Tightening programme by pausing active bond sales until April 2027. The move helped ease upward pressure on government bond yields and could help ease borrowing costs across the broader market. However, while UK rates are on hold for now, we think an increase this year is still a realistic possibility if inflation pressures persist.
Energy prices are a key driver of the recent inflation pressure. Crude oil continues to trade above USD 100 per barrel, while European gas prices have reached historically high levels, which is putting upward pressure on inflation. We therefore believe the Fed will raise rates once more this year. Beyond that, we do not believe this marks the start of a new rate hiking cycle.
Markets remain resilient despite higher rates
The market reaction to the European Central Bank, Fed and BoJ rate hikes was relatively subdued, as the decisions were largely expected. Government bond yields remained close to multi-year highs, with the US 10-year Treasury yield close to 5% and the German 10-year Bund yield around 3.5%. Equity markets posted mostly modest gains over the week, before mainly European markets softened ahead of the weekend while the US dollar strengthened slightly after Fed officials signaled further rate increases may be on the cards.
Against this backdrop of higher bond yields, we maintain our cautious stance on long-dated US Treasuries. We also continue to hold a moderate overweight in equities compared to bonds, with a preference for US and emerging market stocks, reflecting our view that economic growth remains resilient. Our overweight allocation to gold acts as a portfolio diversifier.
US midterms could shape the policy backdrop
The economic impact of higher energy costs is becoming increasingly visible. In the US, rising fuel prices are weighing on consumer confidence and adding to political uncertainty ahead of the November midterm elections. Our base case remains a divided Congress, with the Democrats winning the House and the Republicans retaining control of the Senate. If this happens, it could reduce the likelihood of significant policy changes during the remainder of President Trump’s term, including additional fiscal support and deregulation.
From a market perspective, we do not expect a divided Congress to have a material effect on the earnings trend, meaning broad US equities should remain well positioned. A divided Congress could also reinforce the case for high-quality fixed income. If legislative gridlock reduces the likelihood of significant fiscal expansion, inflation and interest-rate expectations may become even more important for markets. At the same time, higher yields mean bonds now offer a more meaningful source of income than much of the past decade. In a market environment where uncertainty remains elevated, that combination remains attractive.
This week
Can economic growth keep defying Higher rates?
With the latest round of central bank meetings behind us, attention now shifts back to the economic data. The key question remains whether global growth can continue to prove resilient despite higher interest rates and elevated energy costs.
In the US, upcoming data on housing activity, durable goods orders and consumer sentiment (Friday) will provide further insight into the strength of domestic demand. These indicators matter because consumer spending remains a key driver of growth.
Preliminary September purchasing managers’ indices for Europe, the US and Japan will offer an early indication of business activity at the end of the third quarter. Investors will also watch Eurozone consumer confidence (Tuesday), Germany’s Ifo business climate index (Thursday), and the latest consumer sentiment readings from Germany and the UK (both Friday).
The broader question is whether recent signs of economic stabilisation can carry through to year-end. If the data readings above remain resilient, markets may become more comfortable with a period of higher rates.
This week’s global political focus will be on the upcoming meeting between US President Trump and Chinese President Xi Jinping. Relations between the world’s two largest economies matter because they influence trade, supply chains and, in turn, investor confidence. Any signs of improvement could support market sentiment and help ease some of the inflationary pressures linked to trade frictions and supply chains.
Markets will also be watching German political developments following yesterday’s state elections. Chancellor Merz’s CDU party narrowly failed to reach the 5% threshold required to enter the local parliament in the Eastern state of Mecklenburg-Western Pomerania. While the state only represents around 2 % of German’s population, the result may make it harder for Merz to push ahead his reform agenda.